
Why Overpaying for Verification Is the Worst Decision of 2026
Why overpaying for KYC hurts in 2026, and how Didit cuts the bill with $0.33 core KYC, published prices and pay-per-use billing.
Key takeaways
Cutting verification costs to $0.33 per core KYC check releases budget for innovation, marketing, and other key areas, while avoiding the hidden expenses tied to legacy KYC contracts.
Moving to low-cost, pay-per-use KYC streamlines digital onboarding and enhances user experience, minimizing drop-offs and boosting customer retention.
Modern solutions with AI and advanced biometrics provide stronger protection against deepfakes and fraud, ensuring compliance and safeguarding data security.
Tools like Didit unify document verification, facial recognition, and AML Screening, simplifying processes and ensuring compliance with regulations such as eIDAS 2 and GDPR.
Are you still overpaying to verify your customers’ identities? Let us tell you this is the worst decision you could make in 2026: this model is outdated and may be costing you more than you think. While technology advances and new compliance solutions emerge, institutions still locked into expensive, opaque verification contracts are falling behind. It’s time to face it: high fixed fees and hidden costs belong to the past.
Today and tomorrow belong to smart, accessible, and optimized solutions like Didit, a platform with pay-per-use KYC for your business: core KYC costs $0.33 per verification, and every price is published. Why keep paying more for something that should cost less?
If you want to learn more about why overpaying for identity verification is the worst decision of 2026, keep reading!
Why Expensive KYC Is on the Verge of Extinction
In recent years, identity verification has become essential for all kinds of businesses and financial institutions. Banks, fintechs, or gambling platforms understood they had to pay for verifying their customers’ identities, a crucial step to comply with anti-money laundering and counter-terrorist financing rules, as well as other fraud-prevention regulations. Expensive, contract-based KYC has been the standard for many years and was widely accepted by all industry players.
However, the context has changed. While technology moves forward and frauds like deepfakes skyrocket, many companies find themselves stuck in outdated, high-cost verification contracts that continuously drain their resources and fail to offer sufficient protection. The main problem with these traditional KYC systems isn’t just the monthly fees; it’s also all the infrastructure they require to function: this is what we call the hidden costs of traditional KYC models.
The Hidden Costs of Traditional KYC
How much time, money, and general resources do you spend on your organization’s compliance? When we talk about traditional KYC solutions, we typically think of a monthly subscription or a per-verification fee (depending on your plan). However, that’s just the tip of the iceberg. Behind the integration of any identity verification provider, there are expenses that can significantly impact your bottom line.
- Integrations and Infrastructure: Implementing certain traditional KYC services can force you to redesign your entire compliance strategy to make them work efficiently. This means hiring developers, consultants, and integrators who charge hefty hourly fees and whose tasks can take longer than expected. Plus, each new regulatory update may require further changes—meaning more expenses.
- Storage and Processing Capacity: Every identity verification solution requires collecting, storing, and processing a substantial volume of sensitive data, such as ID document photos, selfie videos for liveness checks, and other personal details. If your provider charges per volume or relies on third-party servers that require your own encryption systems, this becomes a recurring bill.
- Human Resources and Support: The more complex a verification system, the more staff you need to manage it. And remember, complexity does not necessarily equal security.
When all these factors are added up, the result is a silently but alarmingly high invoice: each small part of the process adds costs and friction for users, slowing your business growth. Worst of all, this investment doesn’t always translate into better security or higher fraud detection rates.
The Risks of Legacy Verification Models
The drawbacks of traditional, high-cost KYC models go beyond your balance sheet. Along with the financial burdens, you must consider reputational risks and user-experience pitfalls that can damage your company’s image.
- Complicated KYC Processes: KYC should be subtle and not disrupt your customers’ user experience. Some traditional providers still rely on old-fashioned verification methods, which can be lengthy, tedious, and last several days, requiring intrusive actions like sending documents, videos, or other personal data.
- Unsecure Systems: The possibility of data breaches exists on almost any platform, and you assume it every time you share information with a third party. However, as we’ve seen, higher spending on KYC doesn’t necessarily mean more security, and many data storage systems are outdated, easily hacked, and lack sufficient encryption measures. In the event of a breach, your company’s reputation will take the hit.
- Loss of User Trust: If a KYC process becomes too intrusive or repeatedly fails during facial recognition, users may view your platform as unreliable. A poor experience during identity verification can turn a potential long-term relationship into an abrupt exit.
The Low-Cost KYC Shift: Is It Really Possible?
If you’re used to opaque pricing, the idea of a company offering transparent pay-per-use KYC at $0.33 per verification might seem far-fetched. However, solutions like Didit have broken the financial barriers that kept many businesses from meeting compliance requirements, democratizing access to a reliable and secure tool for organizations of any size and sector: Our goal is to challenge the KYC industry’s status quo.
Want to learn more about our approach? Alberto Rosas, our CEO, explains how we approach KYC pricing in this blog post.
Four Reasons to Choose Didit’s KYC
Cost-effectiveness is one of the most significant reasons to switch to a low-cost KYC solution like Didit. It can be a game-changer: paying $0.33 per core KYC verification, only for what you use, can transform any business. From November 2026, the Free plan includes $10 of credit every month, so you can test the full flow before you scale. It also helps optimize investment in your compliance department and cut customer acquisition costs.
This last point is crucial: delivering an outstanding user experience. Paying for a service doesn’t guarantee it’s excellent—or even good; it just means you had to pay for it to satisfy KYC and anti-money laundering regulations. With Didit, you’ll provide a better user experience during the digital onboarding process, ultimately boosting customer satisfaction and retention.
Can you imagine spending thousands of dollars a month only to find that your provider doesn’t have the latest fraud detection tools? That’s one of the problems Didit solves. Our mission is to humanize the internet, which is why we use the latest technology to detect tampered or fraudulent documents and deepfakes, keeping your business safer from cybercriminals.
Therefore, Didit positions itself as an identity verification solution that helps institutions comply with anti-money laundering and counter-terrorist financing (AML/FT) regulations, GDPR, or eIDAS 2, the European regulation aiming to establish a framework for people’s digital identity.
How Does Didit Verify Identities?
With Didit, you can verify your users’ identities in a simple, fast, and frictionless way. Our solution is based on three pillars: document verification, facial recognition, and an optional AML Screening service. Everything is done in under 30 seconds.
- Document Verification. Our custom algorithms analyze official documents to detect any tampering or discrepancies. Once the document’s authenticity is confirmed, the data is extracted. Learn more about our document verification here.
- Facial Recognition. Using custom AI, we perform liveness checks to rule out possible deepfakes, masks, or pre-recorded videos. Our AI models also match the user’s face with their various ID documents. Learn more about our facial recognition here.
- AML Screening (Optional). We do real-time checks of various databases worldwide, both national and international, searching for PEPs (Politically Exposed Persons), sanctions, or adverse media. Learn more about our AML Screening service.
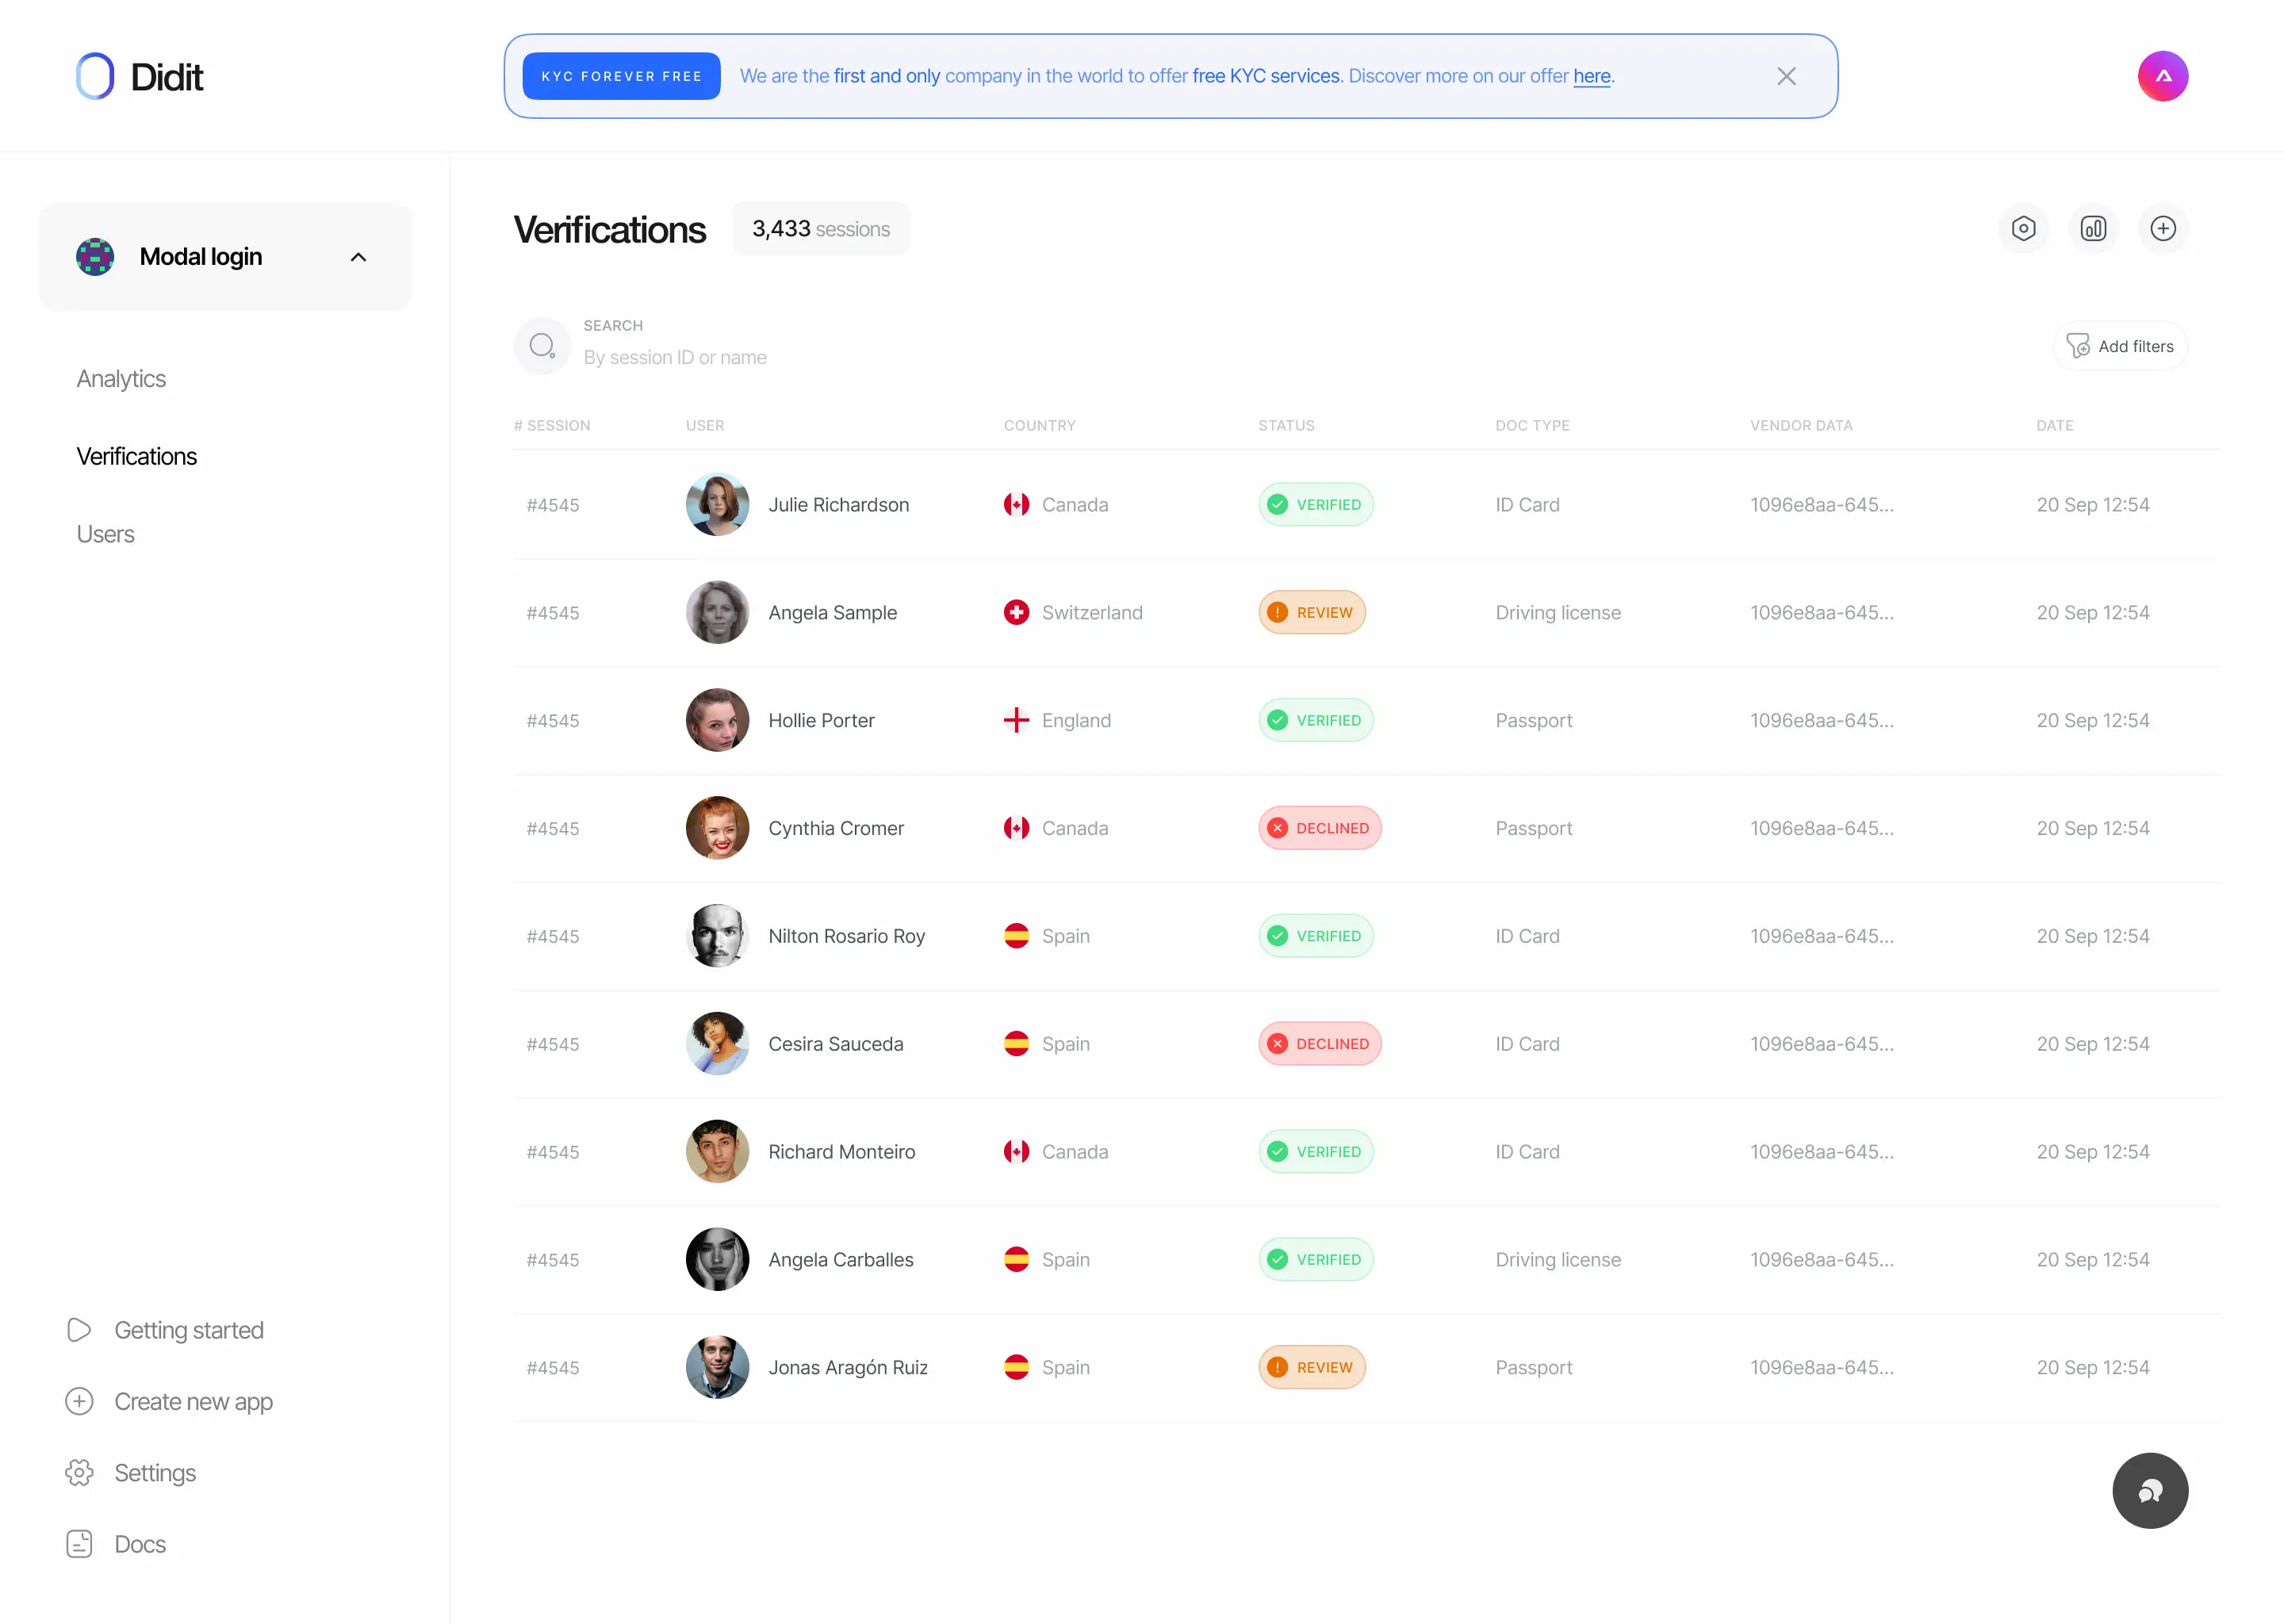
From Didit’s Business Console, you can monitor the status of all identity verification processes in real time on a single screen, tracking your business’s overall security at any moment.
Conclusion: The Future of KYC Is Accessible
With fraud at historic highs (and still rising every year), continuing to overpay for KYC makes no sense in 2026. At Didit, we believe identity verification should be within reach of every business, and that’s our commitment. Our solution cuts the costs tied to KYC and provides a better user experience for both institutions and customers.
The future demands affordable, transparent solutions. Paying per use, at published prices, is a savvy move for any compliance strategy. It’s time to leave the past behind and welcome Didit: the future of KYC is accessible, and you’re just one click away from adopting it.
Related articles
- New pricing from November 1: one plan per product, one balance for everything
- Unico Partners with Didit to Expand Access to State-of-the-Art Identity Verification for SMEs in Brazil
- Didit Closes $7.5M Seed to Build the Infrastructure for Identity and Fraud
- Non-Document Verification in Singapore: MyInfo-Based KYC Without Document Uploads
- Non-Document Verification in Canada: Credit Bureau-Based KYC Without Document Uploads
- Non-Document Verification in the United States: SSN-Based KYC Without Document Uploads